 Mamdani releases plan to combat antisemitism as concerns linger over his criticism of Israel
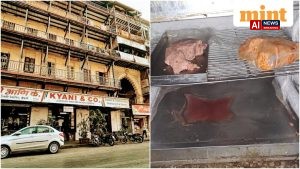
 Cat and rat droppings, flies, dead cockroaches: Why Mumbai’s century-old Kyani & Co faces FDA action
 Have any traffic challan still unpaid? The amount may be added to your electricity bill
 Anne Hathaway says doctor warned her that ‘Hot Ones’ interview could induce early labor
Millions who need flood insurance the most don’t have it as flawed federal program raises prices
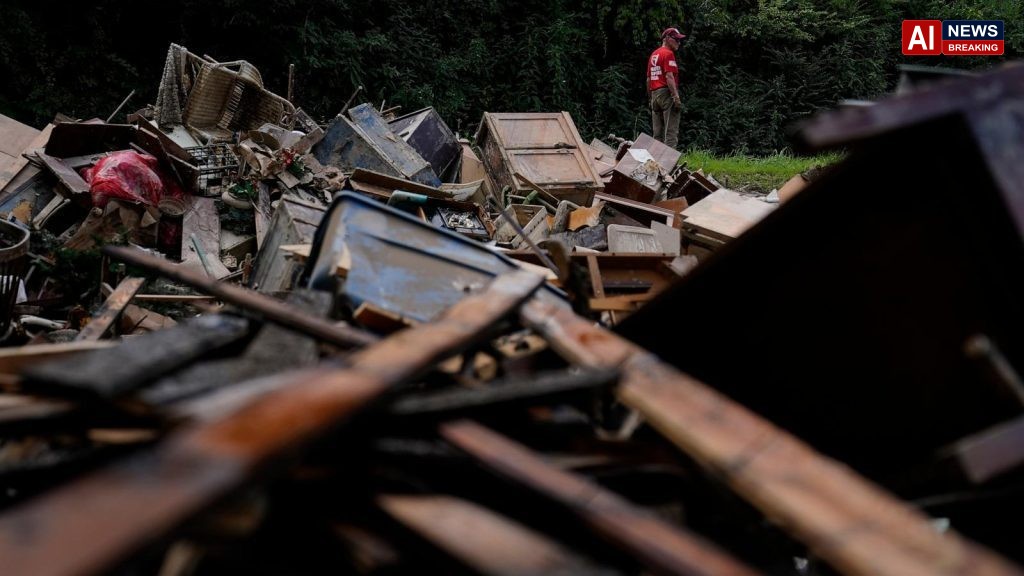
Millions who need flood insurance the most don’t have it as flawed federal program raises prices - AI News Breaking
millions need flood insurance:
Millions of Americans who live in flood‑prone areas still lack the protection that their homes and livelihoods need, a new analysis has found. The gap is widening even as the United States faces a growing threat from extreme weather events, and it is tied to the structure and pricing of the federal flood insurance market. While the National Flood Insurance Program (NFIP), which has been in operation since 1968, is meant to give residents affordable coverage, the recent rise in premiums is turning it into a deterrent rather than a safety net for the most vulnerable communities.The NFIP was created in response to the catastrophic 1927 Mississippi River flood, and it has since insured more than 15 million policies in roughly 80 per cent of U.S..
The program is funded by premiums paid by policyholders and by government subsidies to keep costs low. In principle, the NFIP should be able to absorb the high cost of catastrophic losses that would otherwise overwhelm private insurers. In practice, however, the program has struggled to keep pace with the escalating frequency and severity of flooding events caused by climate change, leading to higher costs for policyholders and an increasing number of uninsured homes.Data released this month by the Federal Emergency Management Agency (FEMA) show that, between 2015 and 2023, the average NFIP premium for a single–family home rose by 18 per cent..
That figure masks a more uneven reality: premiums in the most flood‑prone regions have surged by as much as 30 per cent, while homes in lower‑risk areas have seen smaller increases. The cost creep is a direct reflection of the fact that flood risk is not static. As sea levels rise and storm intensity grows, FEMA has had to re‑price its risk models, a move that has transferred more of the financial burden onto homeowners.One of the main drivers of the rising premiums is the program’s reliance on a fixed underwriting methodology that does not fully capture the changing realities on the ground..
The NFIP uses a three‑step process to determine rates: first, a flood insurance rate map (FIRM) is produced for each community, showing the probability of flooding for different elevations; second, the maps are used to calculate a baseline risk; and finally, a cost‑plus model is applied to arrive at a final premium. Critics argue that this process is slow to respond to new data. By the time a revised FIRM is published, the underlying risk may have already changed.The delay is significant in a world where climate projections can change dramatically within a decade..
For example, the Pacific Northwest, once considered a low‑risk area, has seen a 40 per cent increase in projected annual flood losses since 2010. Communities in such regions have reported that their flood insurance premiums have ballooned by more than 20 per cent in the past three years, even though many residents had not experienced a flood in their lifetime. The mismatch between perceived risk and actual risk has made the NFIP less attractive to homeowners, especially in lower‑income brackets.The affordability problem is compounded by the fact that many people simply cannot afford the premiums even before they rise..
According to the American Community Survey, about 20 per cent of households in flood‑prone counties spend more than 10 per cent of their income on housing costs. Adding a flood insurance premium on top of that can push families beyond the 30 per cent threshold that defines housing affordability, pushing them into financial precarity. When the price of flood protection exceeds what a family can reasonably pay, the logical, if unfortunate, outcome is to forgo coverage entirely.The decision not to purchase flood insurance can have devastating consequences..
In the wake of Hurricane Florence in 2018, for instance, a town in North Carolina that had no NFIP coverage suffered an average loss of $400,000 per home in uninsured claims. Those same houses would have paid a total of just $5,000 for a year’s insurance. The difference between protected and unprotected households is stark, and the financial gap widens when a flood event leads to extended periods of displacement and costly repairs.In an effort to address the affordability crisis, FEMA has launched a series of initiatives over the past five years, such as the Premium Cap program that limits the maximum premium a homeowner can pay..
Yet the cap is set at a level that still excludes the most economically vulnerable. A recent report by the Center for Disaster Philanthropy found that 42 per cent of low‑income homeowners in high‑risk counties are still uninsured because the capped premium remains out of reach. The cap, while well‑meaning, does not alter the underlying risk model or the fact that the NFIP’s cost structure forces higher premiums for those living in the greatest danger.The political context cannot be ignored..
The NFIP was originally designed to encourage homeowners in high‑risk areas to purchase insurance, thereby spreading the financial risk and reducing the burden on local governments. However, the program has become entangled in a complex web of federal subsidies, local tax incentives, and community resilience projects. When local governments receive grants to reduce flood risk, such as through levee reinforcement or green infrastructure, the expectations for NFIP coverage can shift, sometimes leading to a “free rider” effect where residents rely on public works rather than private insurance..
This dynamic can undermine the intended risk sharing mechanism, creating a shortfall in funding that forces premium increases.A growing body of research suggests that the NFIP’s current model is not sustainable in the face of climate change. The American Association of State Floodplain Managers has called for a comprehensive overhaul of the program, recommending that FEMA adopt a more market‑based approach, including the use of catastrophe bonds and private‑sector partnerships. The idea is to transfer some of the catastrophic risk to the capital markets, thereby reducing the need for heavy government subsidies and allowing for more competitive pricing.However, a shift toward market‑based solutions would need to be carefully managed..
Flood risk is notoriously difficult to price accurately, especially in rural areas where data is scarce. Without robust data, insurers may price risk too high, repeating the affordability problem that has plagued the NFIP. Moreover, any move that reduces government involvement risks leaving the poorest communities even more , as private insurers are less likely to write policies in areas that are perceived as high risk but low profitability.The human impact of these policy decisions is profound..
In Louisiana, where the Mississippi River and Gulf Coast floodplain intersect, a study by the University of New Orleans found that 65 per cent of low‑income households in the most at‑risk parishes lack flood insurance. When the 2023 spring floods hit, these families faced not only the loss of property but also the financial strain of rebuilding without insurance coverage.
This development highlights evolving dynamics and may have broader implications in the near term.