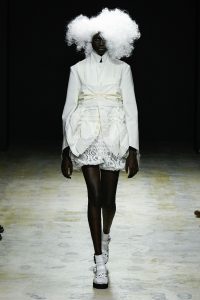
 Tao Tokyo Spring 2027
 Karnataka SIR: Teaching on the back burner
 Trump administration offers mixed messages on limits to Ukraine’s Starshield access
 US Treasury proposes a rule to crack down on high-tech investments in China, other adversaries
 Calley Means, a key MAHA advocate, resigns as a top RFK Jr. adviser
In Trump’s Russian Oil Deal, Middle East Funds Are the Biggest Owners
**
trumps russian deal middle:
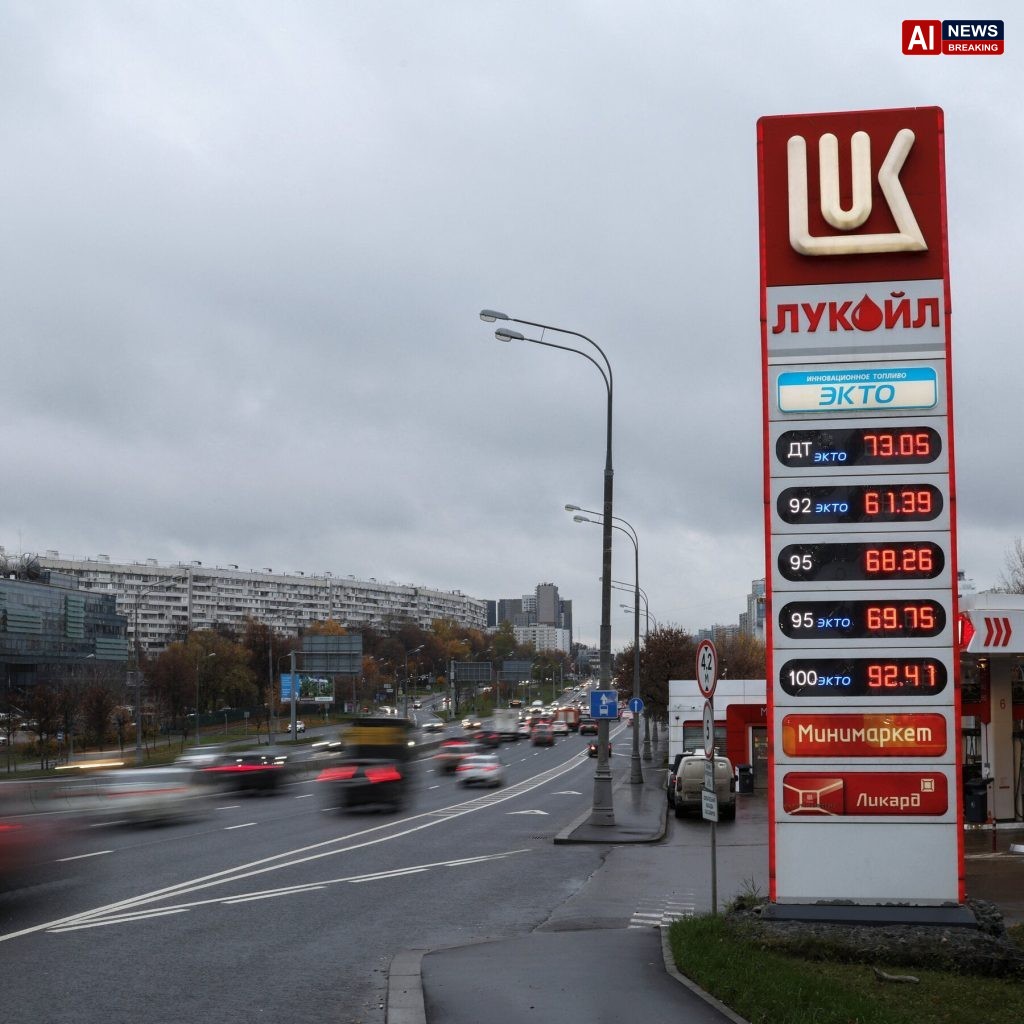
The proposed sale of a vast swathe of Russian oil assets, brokered by former President Donald Trump’s private enterprise, has attracted intense scrutiny after documents revealed that the majority of the anticipated ownership would be held by a consortium of Middle Eastern investors. The deal, valued at several billion dollars, would transfer control of refineries, pipelines and storage facilities in the western part of the Russian Federation to a partnership that includes sovereign wealth funds from the United Arab Emirates, Qatar and Saudi Arabia, as well as private financiers with longstanding commercial links to the United States. While the transaction is still in the negotiation phase, the composition of the prospective owners has raised questions about geopolitical implications, potential conflicts of interest and the role of former U.S..
officials who are alleged to have facilitated introductions between the parties.The deal was first reported in a filing submitted to the Russian Federal Antimonopoly Service in early June, outlining a structure in which Trump’s company, Trump International Energy Holdings, would act as the primary conduit for the purchase. According to the filing, the Middle Eastern consortium would acquire roughly 70 per cent of the equity, leaving the remaining 30 per cent to be split between Trump’s firm and a small group of European investors. The assets in question include the Krasnodar oil terminal on the Black Sea, a network of pipelines that feed into the terminal, and several inland refineries that have been underperforming since the onset of Western sanctions in 2022.The involvement of Middle Eastern sovereign wealth funds is not unprecedented in the energy sector, but the scale of this particular acquisition is unusual..
The United Arab Emirates’ Abu Dhabi Investment Authority (ADIA) is reported to be the largest single contributor, committing an estimated $1.2 billion. Qatar Investment Authority (QIA) and the Public Investment Fund (PIF) of Saudi Arabia are each slated to invest roughly $800 million. These figures represent a combined commitment of more than $2.8 billion, a sum that would make the consortium one of the largest foreign investors in Russian energy infrastructure since the 2014 sanctions regime was introduced.Analysts say the timing of the deal is significant..
Russian authorities have been seeking ways to circumvent sanctions that limit the ability of Western firms to own or manage strategic oil assets. By selling a majority stake to investors from the Gulf, Moscow hopes to retain operational control while accessing capital that is not subject to the same restrictions. “From Russia’s perspective, this is a pragmatic move to keep the oil flowing and the revenues coming,” said Elena Vasilieva, a senior fellow at the Moscow Center for Strategic Studies..
“The involvement of Gulf investors, who have historically been more tolerant of Russian energy ties, provides a political cover that Western investors cannot offer.”Trump’s role in the transaction has become a focal point for U.S. lawmakers and media outlets. The former president’s private equity firm, which was founded after his departure from the White House, has reportedly acted as an intermediary, arranging meetings between Russian officials and Gulf investors..
Critics argue that the arrangement could constitute a conflict of interest, given Trump’s continued political influence and the presence of former administration officials on his advisory board. Among them is former ary of State Mike Pompeo, who has been listed as a senior consultant for Trump International Energy Holdings since March.Pompeo’s involvement has drawn particular attention because of his previous diplomatic engagements with both Russia and Gulf states. During his tenure as ary, Pompeo oversaw the implementation of sanctions that targeted Russian energy companies, yet now he is allegedly assisting a venture that would effectively dilute those sanctions by channeling ownership to non‑Western entities..
“There is a clear dissonance between the policy actions taken while in office and the private sector activities pursued afterward,” said Karen Andrews, a professor of political ethics at Georgetown University. “If former officials are leveraging their contacts to facilitate deals that could undermine U.S. foreign policy objectives, it raises serious ethical concerns.”The U.S..
Department of the Treasury has not publicly commented on the specific transaction, but it has indicated that any foreign investment in Russian energy assets will be subject to a review under the Office of Foreign Assets Control (OFAC). The review process typically assesses whether the transaction could provide material support to the Russian government or its defense sector, which remains under sanction. Legal experts note that the Gulf investors may argue that their funds are sovereign and therefore exempt from many of the sanctions that apply to private entities..
However, the involvement of a U.S. citizen—Trump—could complicate the assessment, particularly if the deal is deemed to involve “U.S. persons” in a prohibited activity.In Washington, the potential deal has ignited a bipartisan debate over the adequacy of current sanctions legislation..
Representative Adam Smith (D‑WA), a member of the House Foreign Affairs Committee, announced plans to introduce a bill that would expand the definition of “beneficial ownership” to include indirect stakes held through foreign subsidiaries. “We cannot allow a former president to use his name and connections to create a loophole that effectively re‑opens Russia’s oil market to foreign capital,” Smith said in a press briefing. Meanwhile, Republican members of the committee argue that the legislation could deter legitimate investment and hurt U.S..
allies in the Gulf who seek diversification of their portfolios.The financial community is watching the development closely. Several major banks have reportedly been approached to provide financing for the Gulf investors’ share of the purchase, though most have declined to comment. Sources within the banking sector suggest that the risk assessment hinges on the potential for secondary sanctions, which could be imposed on institutions that facilitate transactions deemed to support the Russian energy sector..
“Banks are increasingly cautious about any exposure that could be interpreted as indirect support for Russia’s war machine,” said an unnamed senior compliance officer at a European investment bank.Beyond the immediate financial and legal considerations, the deal could have broader implications for global energy markets. Russia remains one of the world’s largest oil exporters, and the assets in question are strategically located near the Black Sea, a key export route for Russian crude. If the Gulf consortium gains operational control, it could influence shipping patterns, pricing strategies and even the allocation of oil supplies to Europe versus Asia..
Energy analysts warn that a shift in ownership could lead to a re‑routing of cargoes, potentially affecting the balance of supply in regions already grappling with price volatility.Local stakeholders in Russia have expressed mixed reactions. Workers at the Krasnodar terminal, many of whom have faced wage cuts and reduced hours since sanctions took effect, view foreign investment as a possible lifeline. “If the new owners can bring in capital to upgrade the facilities, it could mean more stable jobs for us,” said Ivan Pet.
Updated: October 8, 2026
Summary: A deal in negotiations would see Trump’s firm channel a multibillion‑dollar sale of Russian oil terminals, pipelines and refineries to a Gulf sovereign‑wealth consortium that would take about 70% of the equity, while Trump and European investors retain the rest. The arrangement has sparked U.S. political scrutiny over possible conflicts of interest, sanctions compliance and the broader impact on global energy markets.
By channeling Russian oil assets to Gulf sovereign funds, Moscow is effectively sidestepping Western sanctions while keeping the flow of energy—and the money—under its influence, turning geopolitical leverage into a profit‑driven playbook. Trump’s intermediary role, coupled with former officials on his board,