 A lack of rockets is creating a crisis for space technology companies
 Behind India’s record performance at International Math Olympiad 2024
 El Al flight
 Brazil bans online gambling ahead of election.
 Medical helicopter crashes into Pacific, killing two crew members
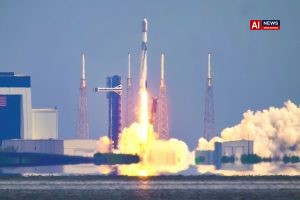
A lack of rockets is creating a crisis for space technology companies
**
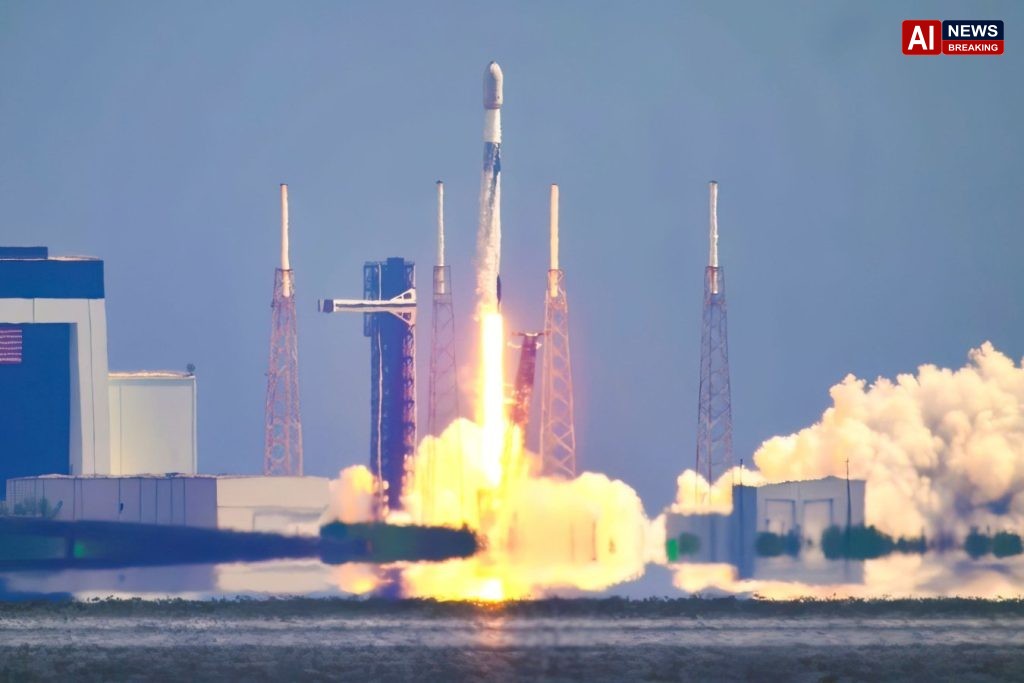
A lack of rockets is creating a crisis for space technology companies - AI News Breaking
lack rockets creating crisis:
A shortage of rockets is turning into a crisis for space technology companies, a situation that could persist for years as shifting priorities, geopolitical tensions and an absence of robust competition converge to undermine the industry’s ability to meet demand.The United States remains the world’s dominant commercial launch provider, but the supply chain that feeds its rocket production has been steadily eroding. At the heart of the problem is a dwindling workforce of highly skilled engineers, technicians and suppliers, many of whom have moved to other sectors or retired. The semiconductor shortage that hit the automotive and consumer electronics industries has also hit aerospace, creating delays in the manufacturing of key components such as avionics, power systems and propulsion hardware..
When a component cannot be sourced on time, an entire launch schedule can be disrupted.SpaceX, the company that has become synonymous with rapid launch cadence, is now recalibrating its priorities. The firm’s starship programme, which promises to ferry humans to Mars, has taken on a central focus, and the company has reduced the frequency of Falcon 9 and Falcon Heavy launches. The decision, driven by a desire to accelerate crewed missions to the Moon and beyond, has left the launch market with a gap that other providers are ill-equipped to fill..
While the starship will eventually become a heavy-lift workhorse, its development timeline is uncertain, and it is unlikely to become operational until the mid‑2020s at the earliest.At the same time, the war in Ukraine has had a ripple effect on the global supply chain for launch hardware. Ukraine is a major producer of high‑performance graphite and carbon fibre, materials that are critical for rocket tanks and structural components. Sanctions and the disruption of transport routes have limited the flow of these materials to European and North American aerospace firms..
The resulting shortage has forced companies such as Arianespace to delay or cancel launches, and has driven up the cost of alternative materials. The geopolitical fallout has also raised concerns about the security of the supply chain, prompting firms to reassess their reliance on single‑source vendors.Compounding these supply‑chain woes is the lack of a competitive launch marketplace. In the early 2000s, several new players emerged in Europe and Japan, offering small‑satellite launch services that disrupted the market..
However, many of those companies have since ceased operations or been acquired, leaving a vacuum that has not yet been filled. In the United States, the only major players are SpaceX and United Launch Alliance, a joint venture between Lockheed Martin and Boeing. The market concentration limits price competition and reduces the incentive for companies to invest in new launch vehicle development.The result is a launch crisis that has already begun to affect customers..
Satellite operators, both commercial and governmental, are finding it difficult to secure launch dates for their payloads. Some have turned to international partners, such as the Indian Space Research Organisation’s GSLV programme, or the Chinese Long March rockets, but these options are not always available or suitable. The delay of a single launch can cascade through an entire constellation of satellites, jeopardising everything from broadband internet to Earth observation missions.The industry’s response has been varied..
Some companies have increased investment in supply‑chain resilience, diversifying their source of critical components and establishing longer lead‑time buffers. Others have accelerated the development of reusable launch vehicles, aiming to reduce the cost per launch and increase launch cadence. Yet the cost of developing a reusable vehicle is high, and the technology is still maturing, which means that the benefits may take years to materialise.Governments are also stepping in to provide support..
The United States has announced funding for research and development of next‑generation launch vehicles, and has created incentive programmes to attract new entrants to the market. In Europe, the European Space Agency has increased its investment in the European Launcher Development Programme, a joint venture between ArianeGroup, Airbus and Arianespace, in an attempt to rebuild a competitive launch ecosystem. However, the timeline for these programmes is long, and they will not immediately resolve the current shortage.The crisis also has implications for the broader space economy..
Space technology is increasingly integrated into everyday life, with satellite communications, navigation, weather forecasting and Earth observation services underpinning critical infrastructure. Any disruption in the launch capacity threatens to delay or cancel projects that have been planned for years, with ripple effects on science, security and commerce. The potential loss of satellites also raises concerns about the long‑term sustainability of space operations, as the increase in satellite launches contributes to growing congestion in orbit.In the face of this uncertainty, stakeholders are exploring alternative strategies..
Some satellite operators are considering satellite buses that can be launched on multiple vehicle types, increasing flexibility. Others are developing smaller, more modular payloads that can be combined into a single launch, reducing the frequency of flights required. Space agencies are also looking at shared launch opportunities, pooling payloads from different countries or organizations onto a single vehicle..
These measures can mitigate the immediate effects of the launch shortage, but they do not address the underlying supply‑chain fragility or market concentration.The long‑term resolution of the crisis will likely depend on a combination of technological innovation, supply‑chain diversification and regulatory support. The development of a new generation of launch vehicles, including more affordable, reusable designs, could increase launch cadence and lower costs, making it easier for a larger number of companies to enter the market. Simultaneously, governments will need to maintain investment in research and development to keep the industry ahead of the curve..
Only by addressing the supply‑chain bottlenecks and encouraging competition can the sector hope to overcome the current launch crisis and secure the future of space technology..
The chronic rocket crunch underscores a looming shift from an industry built on a single super‑power’s dominance to a fragmented, high‑cost ecosystem where satellites become commodities rather than assets. Until supply chains are rewired and new entrants can afford to compete, the very fabric of global connectivity—be it navigation, commerce, or security—will risk becoming an outsourced, fragile service.